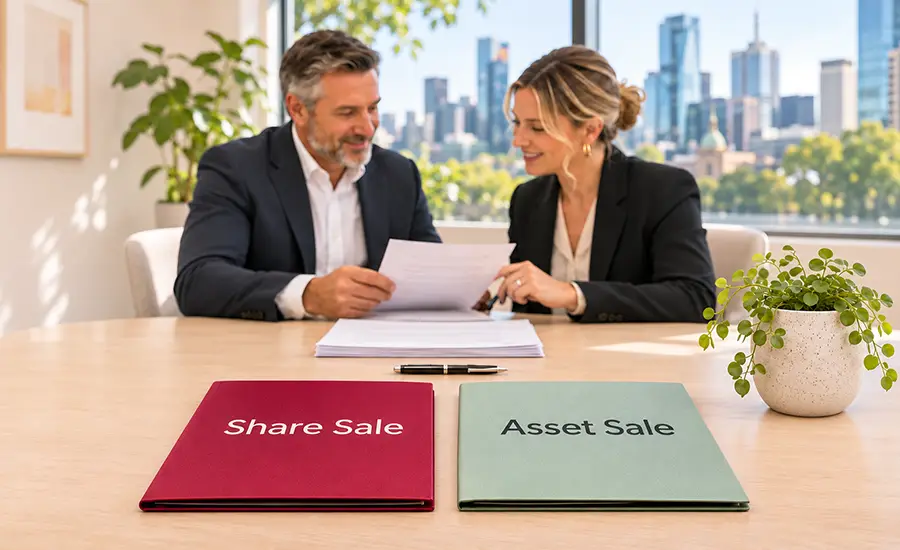
Share sale vs asset sale: Have you got your structure right?
Date: 04 November 2026
Authors: Zahara Bedewi-Hayes - Genuine People
For sellers preparing to sell a business, the structure question is sometimes treated as a formality, but getting it wrong can undo the commercial deal.
What is the difference between a share sale and an asset sale?
Before we dive in, here's a refresher on the difference between a share sale and an asset sale.
In a share sale, the buyer acquires the shares in the entity (or the units in a unit trust), with contracts, licences, liabilities and employees all staying in place. In an asset sale, the buyer acquires specified assets out of the business and assumes specified liabilities.
We have prepared five real-world examples to help sellers understand how contracts, licences and risk drive the decision, rather than a one-size-fits-all rule.
Where a share sale tends to be the better fit
Case study A: Waste management / permit-dependent business
For waste management businesses, environmental and waste licences and permits are frequently non-transferable or require a fresh regulatory application in the new holder's name.
A share sale keeps the licensed entity unchanged, typically avoiding re-application and the risk of a gap in authorisation during transfer.
However, a key consideration is that if the transaction proceeds as a share sale, the buyer inherits historical environmental and compliance liabilities attached to the entity. This makes due diligence, warranties and indemnities, together with security for these, very important.
The same logic applies to other businesses holding non-transferable or hard-to-replicate licences and permits, including certain environmental, transport or specialist regulatory licences.
Case study B: Strata management company
For a strata management company, the business’s value is almost entirely in its portfolio of management contracts with owners corporations or bodies corporate. Transferring each contract would require a separate special meeting of the members of the relevant owners corporation or body corporate.
Transferring dozens or hundreds of contracts in an asset sale is therefore slow and administratively heavy, and risks attrition if an owners corporation declines to consent or decides to re-tender instead.
A share sale avoids triggering assignment provisions, because the contracts stay with the same contracting entity.
That is a generalisation, however. It is still necessary to check contracts for change-of-control clauses that could be triggered even in a share sale, as the management business example below illustrates.
Where an asset sale tends to be the better fit
Case study C: Discretionary trust structure
Where a business operates through a family discretionary trust, a conventional share sale is not available in the same way.
Although a buyer could acquire the shares in the corporate trustee, that acquisition would not, of itself, change the beneficiaries of the discretionary trust. The seller’s family members would remain beneficiaries despite the change in ownership of the trustee.
A buyer will almost certainly not want to acquire a business through a trust whose beneficiaries remain the seller’s family members. For sellers, this makes a sale of shares in the corporate trustee unattractive; changing control of the trustee alone does not deliver the separation from the seller’s family that a buyer is likely to require.
An asset sale, by contrast, lets the buyer acquire the business out of the trust cleanly, leaving the trust and its structure and history with the seller.
For sellers, however, there are important tax considerations and consequences, including a CGT event for the trust and the distribution of proceeds to beneficiaries. These require accounting and tax advice.
Case study D: Management businesses generally (e.g. property/facilities/investment management)
Management agreements and client contracts very commonly include change-of-control clauses that are triggered by a share sale, even though the contracting entity does not legally change.
A share sale can therefore still require counterparty consent under these clauses, removing the main advantage a share sale usually offers.
Where that is the case, an asset sale requiring novation of each contract is often no more administratively burdensome, because consents are needed either way. It also gives the buyer the added benefit of leaving historical liability behind and only paying for what is being transferred.
The scope of the sale also matters. A buyer may only want the management contracts, rather than the whole business. For sellers, an asset sale can help align what is offered with what the buyer is prepared to pay for, while allowing the seller to retain other parts of the business.
For example, a real estate business operating through a single company may undertake both a property sales division and a property management division. If the seller wants to retain the sales division and sell only the management portfolio, an asset sale allows the transaction to focus on the relevant management contracts and associated assets.
Before settling on the sale structure, sellers should therefore consider both what they intend to sell and the consents needed to deliver it. In particular, check key contracts for change-of-control clauses rather than assuming that a share sale will avoid consent requirements.
Honourable mention: Motor vehicle-rich companies
Businesses holding a large fleet of vehicles or other registrable assets face material practical transfer costs and administration in an asset sale that a share sale avoids.
We have covered this scenario in detail in our article on vehicle fleet business sales.
The pattern across all five
For sellers deciding on the most appropriate sale structure, three key questions recur. Can key contracts, licences and permits transfer at all, or only with consent or re-application? Does the entity carry historical risk the buyer wants to avoid? And do change-of-control clauses undercut the usual share sale advantage?
There is no hard-and-fast rule. The right structure follows from the specific business's contracts, licences and risk profile. If you are preparing to sell, reach out to discuss the most appropriate structure for your business.
Frequently asked questions
Yes. A deal can combine a share sale and an asset sale, with some assets carved out and the remainder of the business transferred through a share sale. For sellers, this can help tailor the transaction to what they want to sell and what the buyer wants to acquire.
No. Although the contracting entity stays the same, key contracts may contain change-of-control clauses requiring consent when its shares are sold. As the management business example above shows, sellers should check these clauses before assuming that a share sale avoids third-party consent requirements.
Yes. In a share sale, the employer remains the same, so employees stay employed by the same entity. In an asset sale, employees who move with the business move to a new employer, and transfer-of-business considerations may apply. Sellers should factor employee arrangements into the transaction early.
Differences in pay across the two workforces can also create practical employee relations issues. For example, employees in the business being sold may be covered by an enterprise bargaining agreement (EBA) providing $50 per hour, while a purchaser already operating in the same industry pays its employees $60 per hour under its own EBA. If employees compare rates, the difference may cause dissatisfaction and pressure to align pay, even where the workforces remain employed by separate entities. A purchaser new to the industry, with no existing workforce in that industry, would not face that particular issue, although the applicable employee entitlements still need to be considered.
There is no single answer. The tax outcome depends on the entity type, the seller’s circumstances and the concessions available. Sellers should model the alternatives with their accountant before deciding on a structure, rather than assuming that a share sale or an asset sale will always be more tax-effective.
Profile